The Bombay High Court has quashed the recovery and bank attachment notices, holding that the statutory stay under Section 112(9) of the GST law protects taxpayers challenging only the interest component before the GST Appellate Tribunal. The Court clarified that recovery of disputed GST interest cannot continue during pendency of appeal where the assessee has already paid the entire underlying tax liability and the dispute relates only to interest.
The High Court explained that Section 112(9) grants a statutory stay on recovery of the remaining disputed amount once the appellate requirements under the GST framework are satisfied. Further, no percentage-based pre-deposit of disputed interest is contemplated under Sections 107(6) and 112(8) when the tax itself stands fully discharged and only interest remains in dispute.
The Court clarified that recovery powers under Section 79 are not absolute and cannot override the statutory protection available to an appellant whose challenge is pending before the GST Appellate Tribunal. Accordingly, bank attachment and debit-freeze directions were set aside, with the Court directing authorities to withdraw notices issued to banks and restore normal banking operations of the taxpayer.
Also read Supreme Court Pulls Up Rajasthan Govt. For Withholding Retirement Benefits Of AYUSH Doctor
Briefly, the petitioner, Roadway Solutions India Infra. Ltd, is engaged in construction, maintenance and repair of highways and roads. During a GST investigation, the State GST Department alleged that the company had delayed payment of GST on certain transactions and, therefore, was liable to pay interest under Section 50 of the CGST/MGST Act.
Although the petitioner subsequently paid the entire tax amount, the Department raised interest demands exceeding Rs. 22.12 crore and confirmed the same through adjudication and appellate orders. The petitioner challenged the appellate orders before the GST Appellate Tribunal (GSTAT), where the appeals remained pending. Despite the pendency of those appeals, the Department issued recovery intimations and bank attachment notices under Section 79(1)(c) seeking recovery of the disputed interest amount.
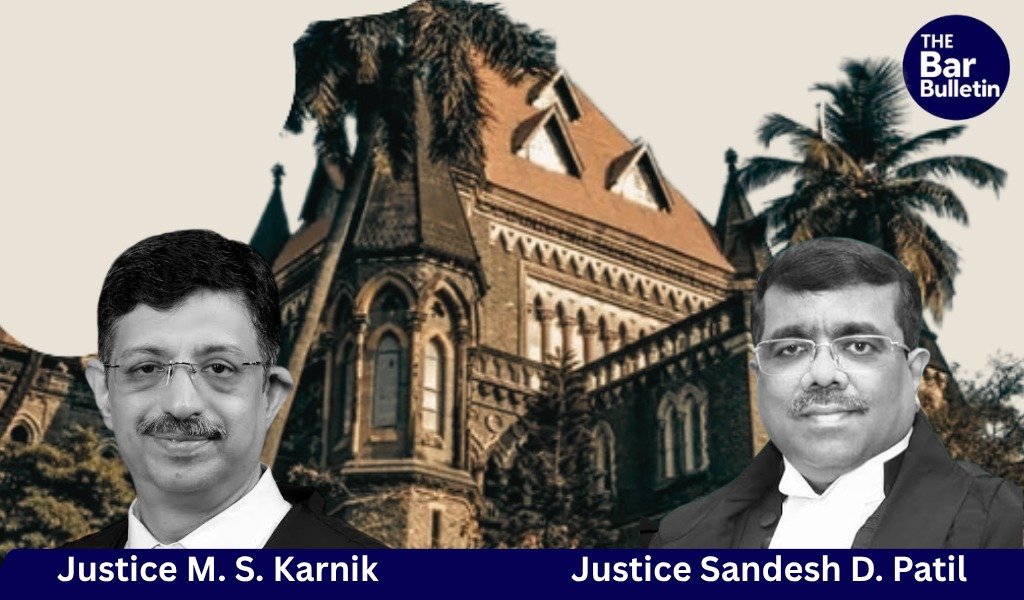
The Division Bench comprising Justice M. S. Karnik and Justice Sandesh D. Patil observed that there was no dispute that the petitioner had already discharged the entire underlying tax liability. The only dispute before the Tribunal related to the levy and computation of interest. The Court noted that Sections 107(6) and 112(8) of the GST law require pre-deposit of disputed tax, but do not prescribe any percentage-based pre-deposit where only interest is under challenge and the entire tax has already been paid. The Court found it significant that both the First Appellate Authority and the GST Appellate Tribunal had entertained the appeals without insisting on any pre-deposit of the disputed interest.
The Court further observed that Section 112(9) specifically provides that once the statutory pre-deposit requirements are complied with, recovery proceedings for the balance disputed amount remain deemed stayed until disposal of the appeal. Therefore, while the Department undoubtedly possesses powers under Section 79 to recover dues, those powers cannot be exercised in a manner that ignores the statutory protection granted to an appellant under Section 112(9) of the CGST/MGST Act.
The Court clarified that it was not expressing any opinion on the merits of the interest demand itself, including issues relating to tax liability, computation of interest, alleged payments under protest, or the petitioner’s claim for refund. All such issues were left open for consideration by the GST Appellate Tribunal.
