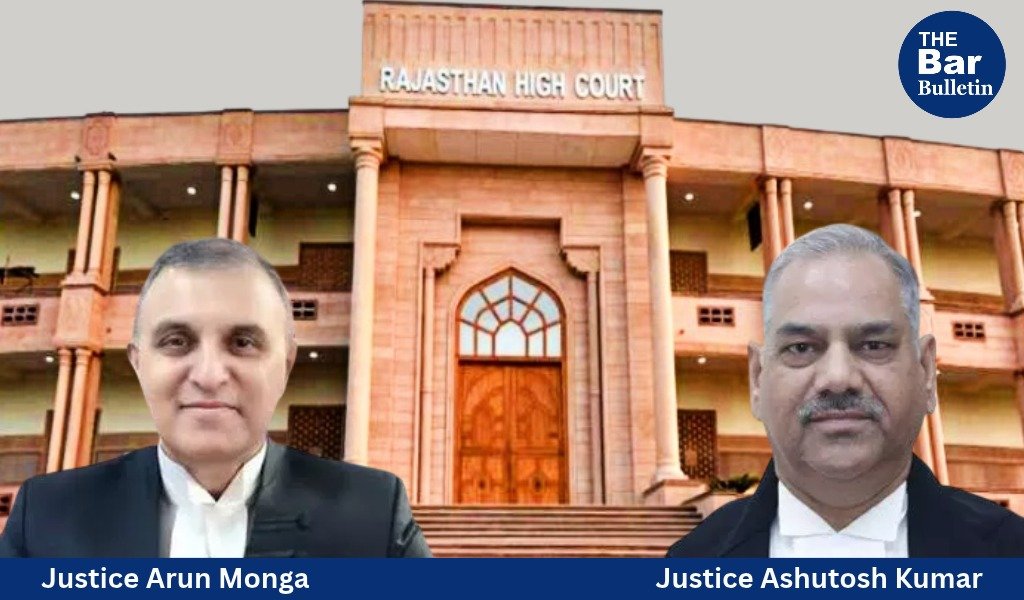
The Rajasthan High Court has upheld the levy of motor vehicle tax on vehicles held by manufacturers and dealers in their possession in the course of business, ruling that manufacturers are liable to pay tax on finished vehicles stocked at their factory premises even if the vehicles are not shown to have used roads in the State.
A Division Bench of Justice Arun Monga and Justice Ashutosh Kumar held that the taxable event under Section 4(1)(d) of the Rajasthan Motor Vehicles Taxation Act, 1951, is possession of motor vehicles by a dealer or manufacturer in the course of business. Proof that any particular vehicle has actually used a road in Rajasthan is not an ingredient of the levy.
The principal question before the Court was whether manufacturers could be taxed on finished vehicles kept inside their factories awaiting despatch to dealers, even where the vehicles had not been shown to have used roads in Rajasthan.
The manufacturers contended that the levy could apply only to vehicles used or kept for use on roads in the State. They argued that vehicles stored within factory premises and subsequently transported outside Rajasthan could not be subjected to the tax. They also challenged the requirement of obtaining trade certificates and argued that the levy was, in substance, a duty of excise on manufacture, falling outside the State Legislature’s competence.
Rejecting these submissions, the Court held that Section 4(1)(d) creates a distinct charge on dealers and manufacturers, with possession of vehicles in the course of business constituting the taxable event. It observed that the provision does not contemplate an inquiry into the actual use of individual vehicles.
The Court further explained that the expression ‘used or kept for use in the State’ in Section 4(1) denotes availability for use and not actual use. It held that vehicles adapted for use on roads and held by a manufacturer within its factory premises in Rajasthan fall within the scope of the levy, irrespective of the State to which they may subsequently be despatched for sale.
On the requirement of a trade certificate, the Court held that Section 39 of the Motor Vehicles Act, 1988, extends to the driving of an unregistered motor vehicle within private premises. A factory yard and internal factory roads fall within the expression ‘any other place’ under the provision. The need for a trade certificate arises when possession of the vehicle is coupled with any movement of that vehicle.
The Court also rejected the challenge to Rule 33 of the Central Motor Vehicles Rules, 1989, observing that the rule confers an exemption from registration rather than imposing a burden. It found it unnecessary to decide whether Rule 33 travels beyond the proviso to Section 39.
On the constitutional challenge, the Court held that the levy was not a duty of excise on manufacture and fell within the legislative competence of the State under Entry 57 of List II of the Seventh Schedule to the Constitution. It further held that, in view of the Supreme Court’s decision in Jindal Stainless Ltd. v. State of Haryana, (2017) 12 SCC 1, compensatory character is not a condition for the validity of a levy under Entry 57. The challenges based on Articles 301 and 304 and the allegation of discrimination under Article 14 were also rejected.
The Court clarified that the taxable events for the manufacturer’s tax under Section 4(1)(d) and the subsequent tax borne by or through the dealer or registered owner are distinct. It therefore rejected the argument that the levy amounted to impermissible double taxation.
However, while upholding the validity of the levy, the Court left open objections concerning the computation of individual assessments. It permitted the manufacturers to challenge the individual assessment orders and demand notices before the appellate authority under Section 14 of the 1951 Act, including on grounds relating to breach of natural justice, the basis for calculating the number of vehicles, and the computation of interest, surcharge and penalty.
The Court directed that such appeals, if filed within eight weeks, be entertained without reference to limitation, excluding the period during which the writ petitions remained pending. Where 50% of the demand had already been deposited pursuant to interim orders, the deposit would be treated as sufficient compliance with the statutory pre-deposit requirement, and no further deposit could be insisted upon for entertaining or hearing the appeals.
The Court further clarified that the power to stay recovery during the pendency of an appeal or revision would lie with the Commissioner under the third proviso to Section 14(2). Recovery of the balance demand would remain stayed in matters where an appeal was filed within the permitted period, until the appeal was decided.
Accordingly, the writ petitions challenging the validity of the statutory provisions and the levy on manufacture and stocking of vehicles were dismissed, while liberty was reserved to challenge the individual assessments on the limited grounds specified by the Court. All connected writ petitions were disposed of, with no order as to costs.
