The Rajasthan High Court (Jodhpur Bench) has upheld the constitutional validity of Rule 36(4) of the CGST Rules, which restricted availment of Input Tax Credit (ITC) where suppliers had not uploaded invoice details in GST returns. The Court held that Rule 36(4) is backed by Sections 16 and 164 of the CGST Act and falls within the Government’s rule-making powers.
Accepting the Revenue’s stand, the Court observed that ITC is a statutory benefit governed by the framework of the GST law and can be subjected to prescribed restrictions aimed at preventing fraudulent claims.
Briefly, the petitions challenged the constitutional validity of Rule 36(4) of the CGST Rules, 2017, which restricted availment of Input Tax Credit (ITC) on invoices not uploaded by suppliers in their GST returns. The petitioners, including registered taxpayers and business associations, argued that they had fulfilled all conditions prescribed under Section 16(2) of the CGST Act and therefore could not be denied ITC merely because their suppliers failed to upload invoice details. One of the petitioners was issued a GST DRC-01A notice seeking reversal of ITC worth about Rs. 1.22 crores due to mismatch with GSTR-2A.
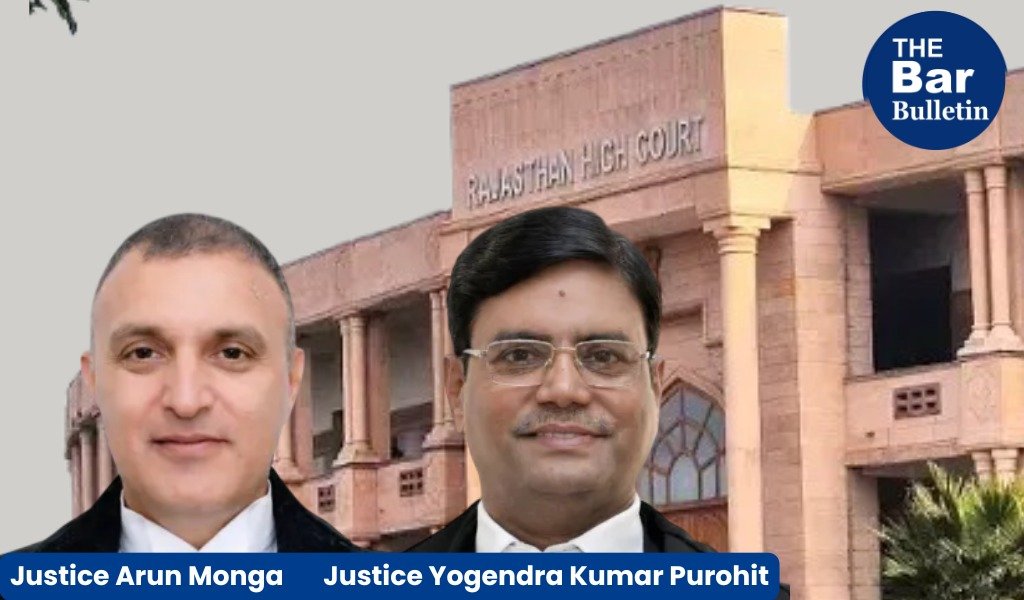
The Division Bench comprising Justice Arun Monga and Justice Yogendra Kumar Purohit noted that the validity of CGST Rule 36(4) had already been upheld by several High Courts, including the Gauhati High Court in M/s High Tech Ecogreen Contractors LLP vs. The Joint Director [WP (C) 4787/2024], the Madras High Court in L. & T Geostructure LLP vs. Union of India [W.P Nos. 5978 and 5983 of 2020] and the Kerala High Court in Nahasshukoor Vs. Assistant Commissioner [W.A. No. 1853 of 2023].
The Court agreed with the reasoning adopted in those decisions and found no ground to take a different view. It observed that Rule 36(4) derives authority from Sections 16 and 164 of the CGST Act and is within the rule-making powers conferred upon the Government. The Court also accepted the view that an unnotified Section 43A could not be treated as the source of power for the impugned rule.
